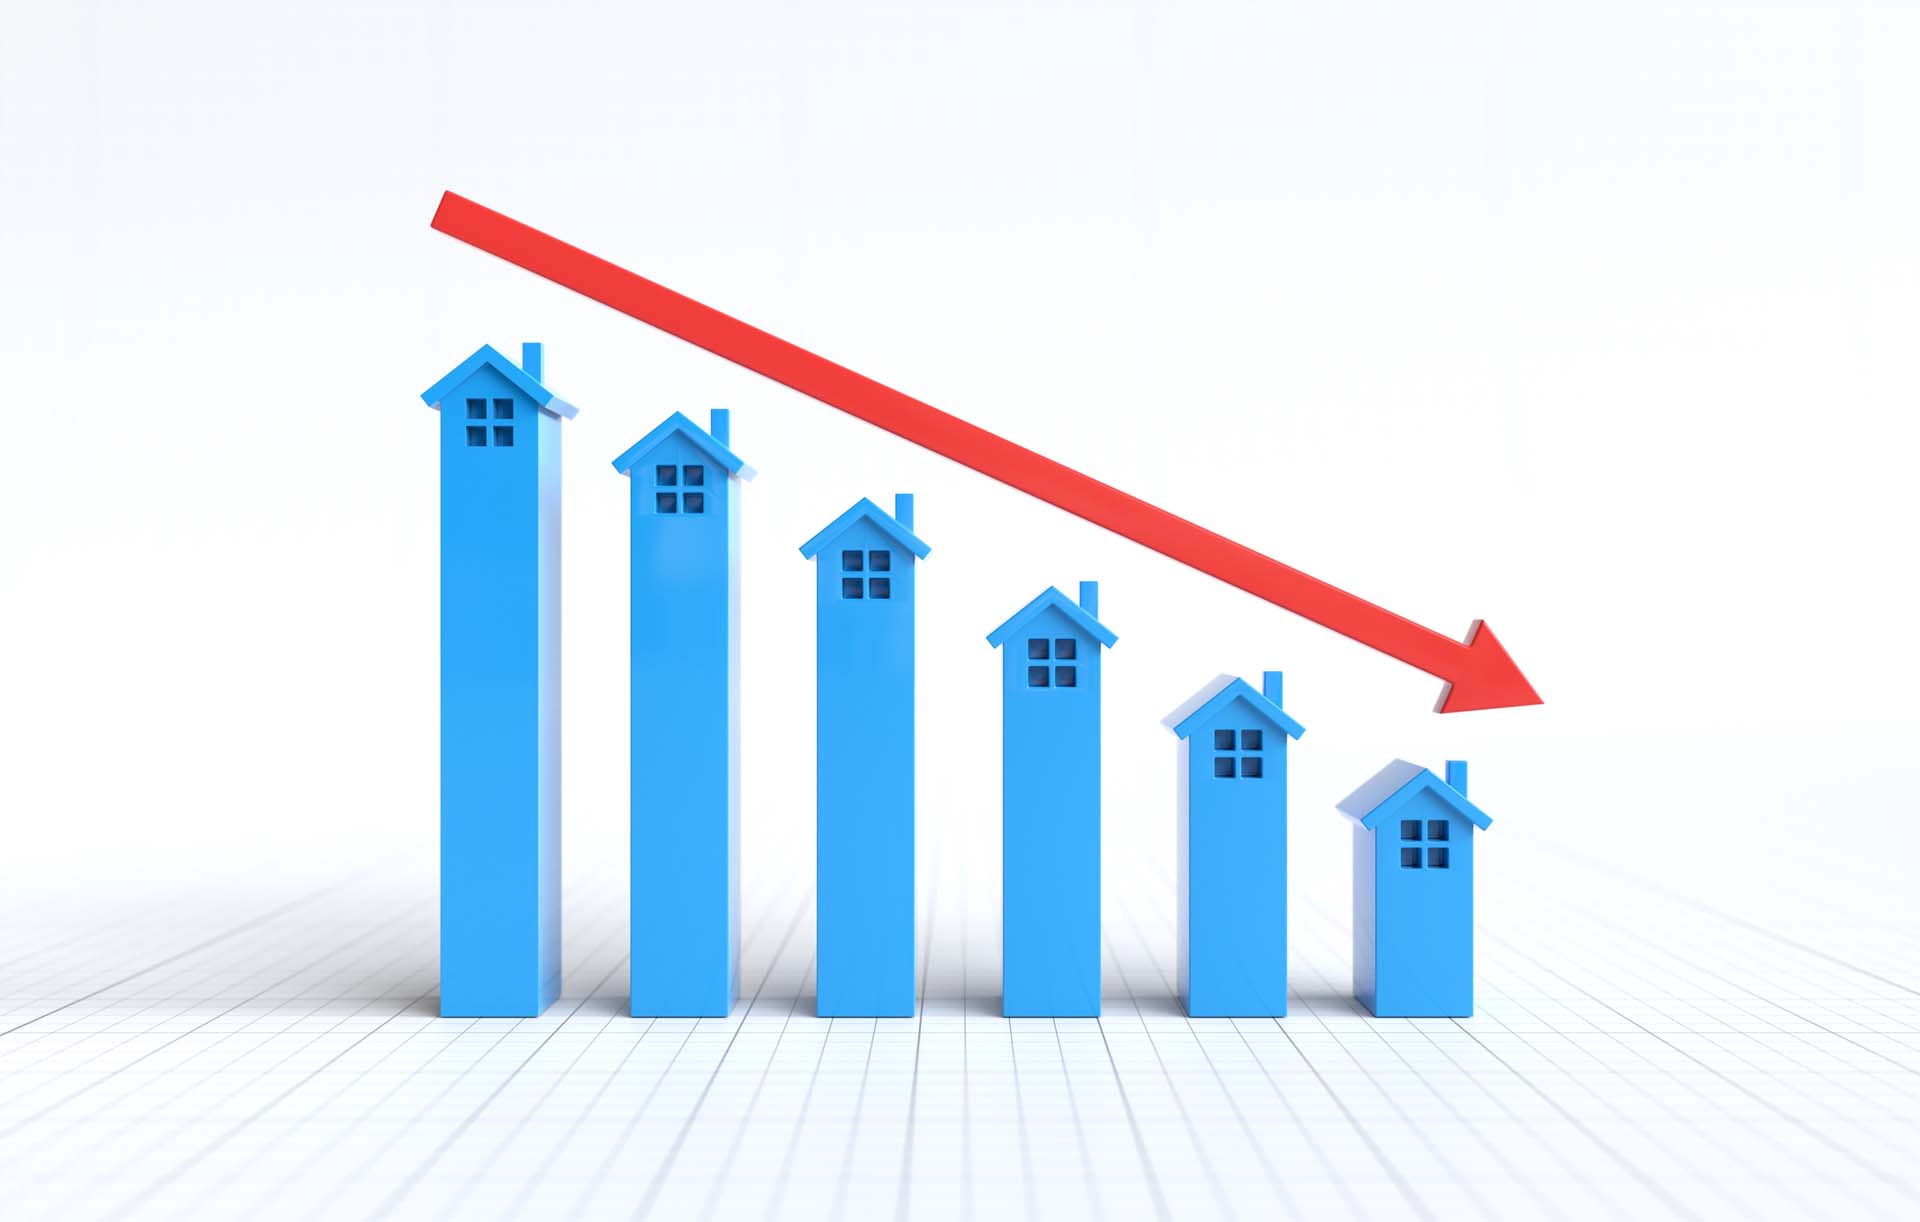
Here’s a market condition that should make every renter feel optimistic: national rents are falling. Vacancy is at the highest level in nearly a decade. Units are sitting on the market for weeks longer than at any point in recent memory — more than twice as long as during the pandemic-era peak.
By every supply-side measure, this should be a renter’s market.
So why does getting approved still feel impossibly difficult for so many people?
The answer has nothing to do with supply. And everything to do with the broken infrastructure that sits between renters and the units sitting empty.
What the Numbers Actually Say
The national multifamily vacancy rate is at a record high. Median rent has pulled back meaningfully from its 2022 peak. The average time it takes to lease an available unit has more than doubled compared to the hottest stretches of the pandemic-era market. Month after month, more units sit vacant while landlords wait — some for the right tenant, some simply unwilling to adjust their ask despite the market conditions around them.
And yet renters — especially those who don’t fit neatly into traditional qualification models — continue to face rejection at similar rates as when the market had zero vacancy and landlords could afford to be highly selective.
That’s not a market failure. That’s a systems failure.
The Market Is Soft. The Screening Model Is Still Rigid.
When the market was tight, landlords had the luxury of running every applicant through a narrow filter and cherry-picking from a long line of prospects. Credit score above a specific threshold. Income at a precise multiple. Pristine rental history. Everything else: next.
The market has changed significantly. The screening model has not changed at all.
That means landlords with vacant units are still filtering out renters who could realistically sustain a lease — gig workers whose income is consistent but non-traditional, people with prior financial hardship who have rebuilt stability, renters with thin credit files who pay every bill on time. All of them measured against a template designed for a different era and a very different market.
The result: units sit empty. Landlords leave revenue on the table. Renters who are genuinely qualified by any reasonable measure get told no. Both sides of this equation are losing.
The Other Side of the Story: Demand Has Also Softened
To be fair to landlords, the caution isn’t entirely irrational. The data shows that demand has genuinely softened. A more uncertain labor market, renewed inflation pressures, and broader economic unease have created conditions where some renters who appear qualified on paper may actually be in a more fragile position than their application suggests.
The answer to that problem isn’t to make the filter more rigid. It’s to make the filter smarter.
The difference between a renter who will reliably pay for the next 12 months and one who won’t isn’t captured by a credit score or an income multiple. It’s captured by a fuller picture of their financial behavior — cash flow patterns, spending stability, income trajectory. That data exists. The industry just hasn’t built the infrastructure to use it.
What a Smarter Market Looks Like
In a market with record vacancy and falling rents, the landlords who win aren’t the ones holding out for a mythical perfect tenant who checks every box on an outdated form. They’re the ones who can accurately assess which renters in the broader pool represent genuine, low-risk opportunities — and move on those tenants quickly with the right terms.
That requires better decisioning, not stricter filtering.
It means knowing that the freelance designer with non-linear income has never missed a payment in three years. It means knowing that the renter with a prior eviction from a period of documented financial hardship is now earning steadily and has rebuilt a payment record that predicts future reliability. It means structuring a lease that reflects the actual risk profile rather than defaulting to rejection because the profile looks unfamiliar.
Where SuddenlySpaces Fits
At SuddenlySpaces, we’re building for exactly this gap — the space between a soft market full of vacant units and the qualified renters who still can’t get access to them.
Our platform gives landlords real visibility into who can actually sustain a lease — not just who clears a credit threshold. It gives renters clarity on what they qualify for today and what’s within reach in the near term. And it gives both sides a foundation for a lease structure that actually works.
Rents are falling. Vacancy is high. Units are sitting empty. The problem isn’t supply. The problem is that the intelligence layer between supply and demand was never built.
That’s exactly what we’re building.
Join the early access list at SuddenlySpaces.com